Nifty 50
- ITC₹267.8011.90 (4.65%)
- HCL Technologies₹1,202-41.10 (-3.31%)
- BSE₹3,170124.00 (4.07%)
- Max Healthcare₹917-23.95 (-2.55%)
- NTPC₹323.408.30 (2.63%)
- Asian Paints₹2,353.40-53.60 (-2.23%)
- Tata Motors PV₹286.457.05 (2.52%)
- HDFC Bank₹706.10-15.10 (-2.09%)
- Bajaj Finance₹971.4523.15 (2.44%)
- Apollo Hospitals₹7,997-136.50 (-1.68%)
- Shriram Finance₹967.6022.60 (2.39%)
- Infosys₹1,017.75-17.25 (-1.67%)
- Eicher Motors₹7,053.50133.50 (1.93%)
- Sun Pharmaceutical₹1,780.80-20.20 (-1.12%)
- Eternal₹319.855.95 (1.90%)
- HDFC Life Insurance ₹529.40-4.80 (-0.90%)
- UltraTech Cement₹10,910200.00 (1.87%)
- Nestle₹1,296.70-11.00 (-0.84%)
- Bharti Airtel₹1,773.6032.50 (1.87%)
- Tata Consumer ₹949.05-7.95 (-0.83%)
- Offerings
- Tools & Platforms
Tools & Calculators
- Open API
- Calculators
- SIP Calculator
- CAGR Calculator
- Compound Interest Calculator
- FD Calculator
- RD Calculator
- EPF Calculator
- Retirement Calculator
- HDFC SIP Calculator
- Mutual Fund Return Calculator
- Lumpsum Calculator
- Step Up SIP Calculator
- ETF SIP Calculator
- Brokerage Calculator
- Equity Margin Calculator
- SWP Calculator
- EMI Calculator
- MTF Calculator
- Margin Pledge Calculator
- Algo Strategy
- Markets
Stocks
F&O
Mutual Funds
- More
Mo͏neyvi͏ew IPO͏
IPO Details
24 Sep 26
28 Sep 26
₹14,994
441
₹32 to ₹34
NSE, BSE
₹1,092 Cr
01 Oct 26
Open Free Demat Account
Open Free Demat Account
Mo͏neyvi͏ew IPO͏ Timeline
Bidding Start
24 Sep 26
Bidding Ends
28 Sep 26
Allotment Finalisation
29 Sep 26
Refund Initiation
30 Sep 26
Demat Transfer
30 Sep 26
Listing
01 Oct 26
About Moneyview Limited
Moneyview Limited is a fintech company that provides a comprehensive digital platform for financial services. Founded in 2017, the company leverages data analytics and technology to provide accessible financial solutions with a focus on personal loans, credit monitoring, and financial management. Its ͏platform functions as a two-sided network that robustly connects 125 million registered users with a wide, diverse range of 42 financial partners, banks, and NBFCs. With a presence across 99.55% of the Indian pin code locations, M͏oneyview’s capital-light, technology-driven business model processes around 200,000 loan applications per day, with minimal human interaction.
Moneyview Limited IPO Overview
Moneyview IPO is a bookbuilding issue of ₹1,091.68 crore, comprising a fresh issue of 22.06 crore shares aggregating to ₹750.00 crore and an offer for sale of 10.05 crore shares aggregating to ₹341.68 crore. The IPO will open for subscription on 24 September 2026 and close on 28 September 2026, with allotment expected to be finalised on 29 September 2026. The tentative listing date is 1 October 2026 on both NSE and BSE. The price band has been fixed at ₹32 to ₹34 per share, with a lot size of 441 shares. Retail investors need to invest a minimum of ₹14,994 for one lot of 441 shares, based on the upper price band. Axis Capital Ltd. is the book-running lead manager, while MUFG Intime India Pvt. Ltd. is the registrar to the issue.
Moneyview Limited Upcoming IPO Details
| Category | Details |
| Issue Type | Book Built Issue IPO |
| Total Issue Size | ₹1,091.68 Crore |
| Fresh Issue | 22.06 crore shares aggregating to ₹750.00 Crore |
| Offer for Sale (OFS) | 10.05 crore shares aggregating to ₹341.68 Crore |
| IPO Dates | 24 September 2026 to 28 September 2026 |
| Price Bands | ₹32 to ₹34 per share |
| Lot Size | 441 Shares |
| Face Value | ₹1 per share |
| Listing Exchange | BSE, NSE |
| Shareholding Pre-Issue | 1,53,96,43,033 shares |
| Shareholding Post-Issue | TBA |
IPO Lots
| Application | Lots | Shares | Amount |
| Retail (Min) | 1 | 441 | ₹14,994 |
| Retail (Max) | 13 | 5,733 | ₹1,94,922 |
| S-HNI (Min) | 14 | 6,174 | ₹2,09,916 |
| S-HNI (Max) | 66 | 29,106 | ₹9,89,604 |
| B-HNI (Min) | 67 | 29,547 | ₹10,04,598 |
Moneyview Limited IPO Reservation
| Investor Category | Shares Offered |
| QIB Shares Offered | Not more than 50% of the Net Offer |
| Retail Shares Offered | Not less than 35% of the Net Offer |
| NII (HNI) Shares Offered | Not less than 15% of the Net Offer |
Moneyview Limited IPO Valuation Overview
| KPI | Value |
| Earnings Per Share (EPS) – Basic | 3.95 |
| Price/Earnings (P/E) Ratio | 8.61 |
| Return on Net Worth (RoNW) | 9.67% |
| Net Asset Value (NAV) | ₹14.67 |
| Return on Equity (RoE) | 15.98% |
| Return on Capital Employed (RoCE) | 21.88% |
| EBITDA Margin | 57.4% |
| PAT Margin | 10.10% |
| Debt to Equity Ratio | 1.78 |
Objectives of the IPO Proceeds
The Net Proceeds from the Fresh Issue are intended to be utilised as per the details provided in the table below:
| Particulars | Amount (in ₹ million) |
| Investment to drive growth in loan disbursals under default loss guarantee (DLG) arrangements | 3250 |
| Investment in WFPL, the Material Subsidiary, for the purpose of augmenting its capital base | 2500 |
| General corporate purposes* | [●] |
*To be determined upon finalisation of the Offer Price and updated in the Prospectus prior to filing with the RoC.
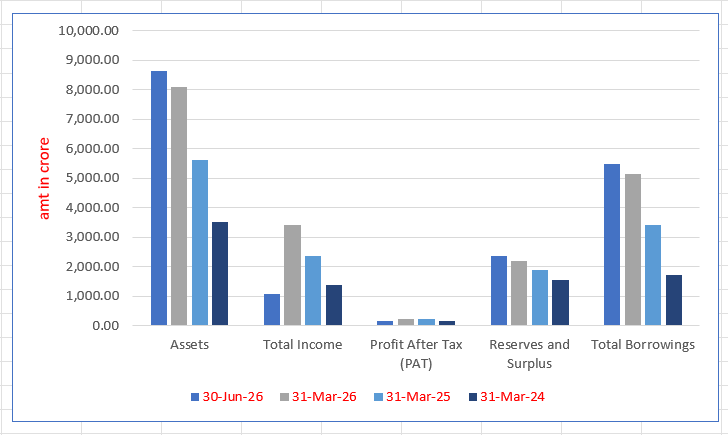
Moneyview Limited Financials (in ₹ crore)
| Particulars | 30 Jun 2026 | 31 Mar 2026 | 31 Mar 2025 | 31 Mar 2024 |
| Assets | 8,641.89 | 8,104.85 | 5,632.42 | 3,519.50 |
| Total Income | 1,065.09 | 3,404.27 | 2,378.53 | 1,389.24 |
| Profit After Tax (PAT) | 173.80 | 242.71 | 240.28 | 171.15 |
| Reserves and Surplus | 2,374.84 | 2,185.06 | 1,878.10 | 1,569.21 |
| Total Borrowings | 5,484.76 | 5,157.04 | 3,413.37 | 1,708.92 |
Moneyview Limited IPO Strengths
1. Large, Growing, and Sticky User Base with a Flywheel Effect
Moneyview Limited benefits from a vast and engaged user base of 125.49 million registered users as of December 2025. This scale creates a powerful flywheel effect, where increased user activity generates more data, which in turn improves its algorithms, leading to better risk assessment and product offerings. This attracts more users and partners, further solidifying its market position and creating a self-reinforcing cycle for sustainable growth.
2. Data-Driven Approach for User Segmentation and Risk Assessment
Moneyview Limited employs a sophisticated data-driven methodology for user segmentation and credit evaluation. By analyzing a wide array of structured and unstructured data, the company can look beyond traditional bureau metrics to assess affordability and intent. This allows for more accurate risk pricing, enabling disciplined credit expansion across a broader user base while maintaining strong portfolio credit quality.
3. Technological and AI Capabilities Enabling Scalable and Efficient Growth
Moneyview Limited leverages advanced AI across its operations, from user onboarding and credit evaluation to collections and customer support. Its AI-powered chatbots, voice-bots, and machine learning models automate workflows, enhance operational efficiency, and improve user experience. This technology-first approach allows the company to scale rapidly with limited incremental costs, driving significant operating leverage.
4. Capital-Light Model with a Diversified Network of Capital Partners
Moneyview Limited operates a highly capital-efficient model by acting as a Loan Service Provider (LSP) for its flagship personal loan product. This generates revenue through fees rather than direct capital deployment, leading to higher returns on equity. The company supports this with deep integrations across 42 financial partners and a diversified funding base of over 100 debt security-holders, ensuring scalable and resilient liquidity.
5. Experienced Management Team with a Track Record of Building and Managing Successful Businesses
The company is led by a management team that uniquely blends financial services expertise with deep technology acumen. This combination is critical for navigating the complex fintech landscape. The team’s long tenure and product-first mindset ensure prudent execution, strong governance, and a consistent focus on innovation, enabling the company to identify and capitalize on new opportunities effectively.
More About Moneyview Limited
Moneyview Limited has established itself as a leading fintech platform in India, fundamentally changing how individuals access and manage financial services. The company’s mission is to make credit accessible to all through a technology-driven, user-centric approach.
1. The Platform and Its Reach:
I. Two-Sided Network: Moneyview operates a powerful two-sided network, connecting over 125.49 million Registered Users with 42 Financial Partners, including banks, NBFCs, and insurers.
II. Pan-India Presence: With a presence in 99.55% of Indian pin codes, the company operates entirely without physical branches, relying on its robust digital infrastructure.
III. Scale of Operations: The platform processes close to 200,000 loan applications per day with minimal human intervention, showcasing its technological prowess.
2. Product Offerings:
The company’s core offering is personal loans, but it has strategically expanded its suite of financial products to capture a larger share of the user’s financial lifecycle. These include:
I. Credit Monitoring: Tools to help users track and improve their credit scores.
II. Expense Tracking & Financial Planning: Features that help users manage their personal finances.
III. New Products: In Fiscal 2025, the company launched eight new products, including earned wage access, home loans, loans against property, credit cards, health and auto insurance, digital gold, and UPI bill payments.
3. Business Model and Financial Discipline:
Moneyview’s business model is built on scalability and resilience. It has demonstrated consistent growth across key metrics, with total income increasing by 71.21% from Fiscal 2024 to Fiscal 2025. The company has simultaneously improved its profitability, with profit before tax rising by 60.97% over the same period. This financial discipline, combined with its capital-light structure, has resulted in a high annualized Return on Equity of 15.98% for the nine months ended December 31, 2025, underscoring its capital efficiency and sustainable growth trajectory.
Industry Outlook
Moneyview Limited operates in India’s rapidly expanding digital lending industry, a sector poised for exponential growth. The Indian fintech market is being driven by a powerful confluence of factors. The country’s young population, rising disposable incomes, and increasing digital literacy are leading to a surge in formal credit demand. This is underpinned by the proliferation of digital public infrastructure like UPI and Aadhaar, and a growing comfort with mobile-first platforms.
The personal loan market is projected to expand to ₹28–31 trillion by Fiscal 2030, with the digital personal loans segment expected to grow at a robust CAGR of 27-29% over the period from Fiscal 2025 to Fiscal 2030.
Within this landscape, the demand for instant, unsecured credit is particularly high. Regulatory developments, such as the RBI’s Digital Lending Guidelines and the expansion of the co-lending framework, have created a clearer operating environment. This clarity is encouraging greater participation from established banks and well-capitalized NBFCs, who are increasingly partnering with technology-led platforms for customer acquisition and loan servicing.
This trend is expected to accelerate the adoption of platform-based models, creating significant growth opportunities for digital lending platforms like Moneyview. The industry’s shift towards a capital-light model further supports scalable growth, as evidenced by the strong performance of leading players in the space.
How Will Moneyview Limited Benefit
1. The company is poised to capitalize on the projected 27-29% CAGR of the Indian digital personal loan market, offering significant headroom for loan volume growth.
2. By expanding its registered user base from 125 million towards the projected 1 billion smartphone users in India by 2030, Moneyview can significantly increase its market penetration.
3. Its capital-light LSP model positions it perfectly to benefit from the increasing participation of banks and NBFCs in the co-lending framework, expanding its partner network and fee income.
4. The launch of eight new financial products in Fiscal 2025 allows Moneyview to cross-sell to its existing user base, increasing user lifetime value and reducing customer acquisition costs.
5. Deepening investments in AI will enhance operational efficiency, further reducing its marketing and operating costs as a percentage of income, thereby driving margin expansion.
6. As its credit rating improves (recently upgraded to ‘A-minus’), the company can reduce its cost of capital, enhancing profitability and financial resilience.
Peer Group Comparison
| Name of Company | Face Value (₹) | Revenue (in ₹ million) | EPS (₹) | NAV (₹ ) | P/E | RoNW (%) |
| Moneyview | 1 | 23,391.46 | 1.60 | 12.98 | N.A. | 12.52 |
| Peer Group | ||||||
| PB Fintech Limited | 2 | 49,772.10 | 7.77 | 140.18 | 193.77 | 5.49 |
| One97 Communications Limited | 1 | 69,004.00 | (10.35) | 235.12 | NA# | (4.42) |
| Bajaj Finance Limited | 2 | 696,835.10 | 268.94 | 1,593.67 | 37.24$ | 16.96 |
| SBI Cards and Payment Services Limited | 10 | 180,722.20 | 20.15 | 145.62 | 38.62 | 13.83 |
Key Strategies for Moneyview Limited
1. Expand the Registered User Base
Moneyview Limited aims to expand its registered user base by capturing a larger share of India’s growing smartphone user population. It plans to achieve this through a holistic marketing strategy that includes optimizing performance marketing, increasing brand-building initiatives, expanding partnership channels, and leveraging the acquisition of Jify to access employee populations via corporate partnerships, all while improving marketing efficiency.
2. Increase User Monetization and Personal Loan Volumes
The company intends to drive monetization by converting a higher percentage of its registered users into active borrowers. It will focus on improving product personalization and leveraging repeat loan growth, which has already increased from 29% in Fiscal 2023 to 59% in the recent period. This strategy aims to sustain the 45.93% CAGR in loan disbursals achieved from Fiscal 2023 to 2025.
3. Expand the User Lifetime Value Through Multi-Product Relationship
Moneyview plans to evolve into a comprehensive fintech app by broadening its product offerings beyond personal loans. By cross-selling new products like home loans, credit cards, and insurance to its existing user base, the company aims to capture a larger share of the user’s financial lifecycle, thereby enhancing user lifetime value and building deeper, long-term customer relationships.
4. Deepen Financial Partner Ecosystem for Product and Market Expansion
A key strategy is to strategically onboard new financial partners, including banks and NBFCs, to expand product breadth and market reach. By strengthening its network for lending, insurance, and payments, Moneyview aims to offer a wider suite of solutions. Deepening relationships with existing partners to offer multiple products will further solidify its platform’s value proposition.
5. Continue to Invest Heavily in AI to Improve Operational Efficiencies
Moneyview will continue to heavily invest in AI to enhance all aspects of its operations. This includes using AI to simplify user onboarding, improve credit evaluation models, power empathetic AI voice-bots for collections, and deliver 24/7 customer support. These AI-driven initiatives are expected to drive employee productivity, automate workflows, and expand operating leverage.
6. Drive Income Growth and Cost Efficiency to Further Enhance Profitability
The company’s final strategy is to focus on sustained financial improvement. It aims to drive income growth through user and volume expansion, improve operational efficiency by reducing marketing and operating costs, strengthen credit quality through advanced data models, and reduce the cost of capital by diversifying its lender base and leveraging its improved credit rating.
SWOT Analysis of Mo͏neyvi͏ew IPO͏
Strength and Opportunities
- Large, growing, sticky user base of 125.49 million Registered Users
- Data-driven approach for user segmentation and risk assessment
- Advanced technological and AI capabilities enabling scalable growth
- Capital-light model with a diversified network of 42 capital partners
- Experienced management team with a track record of success
- Strong financial performance with 71.21% revenue growth in FY25
- Expanding product portfolio beyond personal loans to enhance lifetime value
- Growing Indian digital lending market with a projected 27-29% CAGR
- Opportunity to increase monetization from 7.75% of Registered Users
- Deepening financial partner ecosystem for product and market expansion
Risks and Threats
- Concentrated revenue stream heavily dependent on personal loans
- Intense competition from other established fintech and traditional lenders
- Regulatory changes in digital lending could impact operational model
- High reliance on third-party financial partners for loan capital
- Risk of higher-than-expected credit defaults in the loan portfolio
- Cybersecurity threats and data privacy concerns inherent to the fintech sector
- Economic downturns could affect borrower repayment capabilities
- Potential reputational risk from collection practices of partner entities
- Future funding costs may rise, impacting profitability
- Dilution of key metrics post-IPO due to substantial fresh issue
Upcoming IPO News


Explore IPO Opportunities
Explore our comprehensive IPO pages to stay updated on the latest trends and insights.


More About Moneyview Limited
Moneyview Limited has established itself as a leading fintech platform in India, fundamentally changing how individuals access and manage financial services. The company’s mission is to make credit accessible to all through a technology-driven, user-centric approach.
The Platform and Its Reach:
- Two-Sided Network: Moneyview operates a powerful two-sided network, connecting over 125.49 million Registered Users with 42 Financial Partners, including banks, NBFCs, and insurers.
- Pan-India Presence: With a presence in 99.55% of Indian pin codes, the company operates entirely without physical branches, relying on its robust digital infrastructure.
- Scale of Operations: The platform processes close to 200,000 loan applications per day with minimal human intervention, showcasing its technological prowess.
Product Offerings:
The company’s core offering is personal loans, but it has strategically expanded its suite of financial products to capture a larger share of the user’s financial lifecycle. These include:
- Credit Monitoring: Tools to help users track and improve their credit scores.
- Expense Tracking & Financial Planning: Features that help users manage their personal finances.
- New Products: In Fiscal 2025, the company launched eight new products, including earned wage access, home loans, loans against property, credit cards, health and auto insurance, digital gold, and UPI bill payments.
Business Model and Financial Discipline:
Moneyview’s business model is built on scalability and resilience. It has demonstrated consistent growth across key metrics, with total income increasing by 71.21% from Fiscal 2024 to Fiscal 2025. The company has simultaneously improved its profitability, with profit before tax rising by 60.97% over the same period. This financial discipline, combined with its capital-light structure, has resulted in a high annualized Return on Equity of 15.98% for the nine months ended December 31, 2025, underscoring its capital efficiency and sustainable growth trajectory.
Industry Outlook
Moneyview Limited operates in India’s rapidly expanding digital lending industry, a sector poised for exponential growth. The Indian fintech market is being driven by a powerful confluence of factors. The country’s young population, rising disposable incomes, and increasing digital literacy are leading to a surge in formal credit demand. This is underpinned by the proliferation of digital public infrastructure like UPI and Aadhaar, and a growing comfort with mobile-first platforms.
The personal loan market is projected to expand to ₹28–31 trillion by Fiscal 2030, with the digital personal loans segment expected to grow at a robust CAGR of 27-29% over the period from Fiscal 2025 to Fiscal 2030.
Within this landscape, the demand for instant, unsecured credit is particularly high. Regulatory developments, such as the RBI’s Digital Lending Guidelines and the expansion of the co-lending framework, have created a clearer operating environment. This clarity is encouraging greater participation from established banks and well-capitalized NBFCs, who are increasingly partnering with technology-led platforms for customer acquisition and loan servicing.
This trend is expected to accelerate the adoption of platform-based models, creating significant growth opportunities for digital lending platforms like Moneyview. The industry’s shift towards a capital-light model further supports scalable growth, as evidenced by the strong performance of leading players in the space.
How Will Moneyview Limited Benefit
- The company is poised to capitalize on the projected 27-29% CAGR of the Indian digital personal loan market, offering significant headroom for loan volume growth.
- By expanding its registered user base from 125 million towards the projected 1 billion smartphone users in India by 2030, Moneyview can significantly increase its market penetration.
- Its capital-light LSP model positions it perfectly to benefit from the increasing participation of banks and NBFCs in the co-lending framework, expanding its partner network and fee income.
- The launch of eight new financial products in Fiscal 2025 allows Moneyview to cross-sell to its existing user base, increasing user lifetime value and reducing customer acquisition costs.
- Deepening investments in AI will enhance operational efficiency, further reducing its marketing and operating costs as a percentage of income, thereby driving margin expansion.
- As its credit rating improves (recently upgraded to ‘A-minus’), the company can reduce its cost of capital, enhancing profitability and financial resilience.
Peer Group Comparison
| Name of Company | Face Value (₹) | Revenue (in ₹ million) | EPS (₹) | NAV (₹ ) | P/E | RoNW (%) |
| Moneyview | 1 | 23,391.46 | 1.60 | 12.98 | N.A. | 12.52 |
| Peer Group | ||||||
| PB Fintech Limited | 2 | 49,772.10 | 7.77 | 140.18 | 193.77 | 5.49 |
| One97 Communications Limited | 1 | 69,004.00 | (10.35) | 235.12 | NA# | (4.42) |
| Bajaj Finance Limited | 2 | 696,835.10 | 268.94 | 1,593.67 | 37.24$ | 16.96 |
| SBI Cards and Payment Services Limited | 10 | 180,722.20 | 20.15 | 145.62 | 38.62 | 13.83 |
Key Strategies for Moneyview Limited
Expand the Registered User Base
Moneyview Limited aims to expand its registered user base by capturing a larger share of India’s growing smartphone user population. It plans to achieve this through a holistic marketing strategy that includes optimizing performance marketing, increasing brand-building initiatives, expanding partnership channels, and leveraging the acquisition of Jify to access employee populations via corporate partnerships, all while improving marketing efficiency.
Increase User Monetization and Personal Loan Volumes
The company intends to drive monetization by converting a higher percentage of its registered users into active borrowers. It will focus on improving product personalization and leveraging repeat loan growth, which has already increased from 29% in Fiscal 2023 to 59% in the recent period. This strategy aims to sustain the 45.93% CAGR in loan disbursals achieved from Fiscal 2023 to 2025.
Expand the User Lifetime Value Through Multi-Product Relationship
Moneyview plans to evolve into a comprehensive fintech app by broadening its product offerings beyond personal loans. By cross-selling new products like home loans, credit cards, and insurance to its existing user base, the company aims to capture a larger share of the user’s financial lifecycle, thereby enhancing user lifetime value and building deeper, long-term customer relationships.
Deepen Financial Partner Ecosystem for Product and Market Expansion
A key strategy is to strategically onboard new financial partners, including banks and NBFCs, to expand product breadth and market reach. By strengthening its network for lending, insurance, and payments, Moneyview aims to offer a wider suite of solutions. Deepening relationships with existing partners to offer multiple products will further solidify its platform’s value proposition.
Continue to Invest Heavily in AI to Improve Operational Efficiencies
Moneyview will continue to heavily invest in AI to enhance all aspects of its operations. This includes using AI to simplify user onboarding, improve credit evaluation models, power empathetic AI voice-bots for collections, and deliver 24/7 customer support. These AI-driven initiatives are expected to drive employee productivity, automate workflows, and expand operating leverage.
Drive Income Growth and Cost Efficiency to Further Enhance Profitability
The company’s final strategy is to focus on sustained financial improvement. It aims to drive income growth through user and volume expansion, improve operational efficiency by reducing marketing and operating costs, strengthen credit quality through advanced data models, and reduce the cost of capital by diversifying its lender base and leveraging its improved credit rating.
How to apply IPO with HDFC SKY?
Follow these simple steps to apply for an IPO through HDFC SKY. Secure your investments and explore new opportunities with ease by accessing the IPOs available on the platform.
- 1Login to your HDFC SKY Account
- 2Select Issue
- 3Enter Number of Lots and your Price.
- 4Enter UPI ID
- 5Complete Transaction on Your UPI App
FAQs on Moneyview IPO
What is the issue size of the Moneyview IPO?
When will the Moneyview IPO open and close?
What is the minimum investment for the Moneyview IPO?
On which stock exchanges will Moneyview be listed?
How can I apply for the Moneyview Limited IPO?
Invest Anytime, Anywhere
By signing up I certify terms, conditions & privacy policy