Nifty 50
- Bharti Airtel₹1,909.3017.60 (0.93%)
- Nestle₹1,192.40-31.50 (-2.57%)
- Eternal₹313.250.90 (0.29%)
- Power Grid Corp₹246.35-5.80 (-2.30%)
- Bajaj Finance₹926.900.90 (0.10%)
- Coal India₹398.25-9.25 (-2.27%)
- ONGC₹225.790.17 (0.08%)
- SBI Life Insurance ₹1,625.20-35.80 (-2.16%)
- Kotak Mahindra Bank₹437.800.00 (0.00%)-
- Trent₹2,762.30-59.70 (-2.12%)
- Max Healthcare₹803.15-16.75 (-2.04%)
- Bharat Electronics₹365-6.20 (-1.67%)
- HDFC Life Insurance ₹531.05-8.60 (-1.59%)
- Hindalco Industries₹878.80-14.05 (-1.57%)
- Asian Paints₹2,283.60-35.80 (-1.54%)

- Offerings
- Tools & Platforms
Tools & Calculators
- Open API
- Calculators
- SIP Calculator
- CAGR Calculator
- Compound Interest Calculator
- FD Calculator
- RD Calculator
- EPF Calculator
- Retirement Calculator
- HDFC SIP Calculator
- Mutual Fund Return Calculator
- Lumpsum Calculator
- Step Up SIP Calculator
- ETF SIP Calculator
- Brokerage Calculator
- Equity Margin Calculator
- SWP Calculator
- EMI Calculator
- MTF Calculator
- Margin Pledge Calculator
- Algo Strategy
- Markets
Stocks
F&O
Mutual Funds
- More
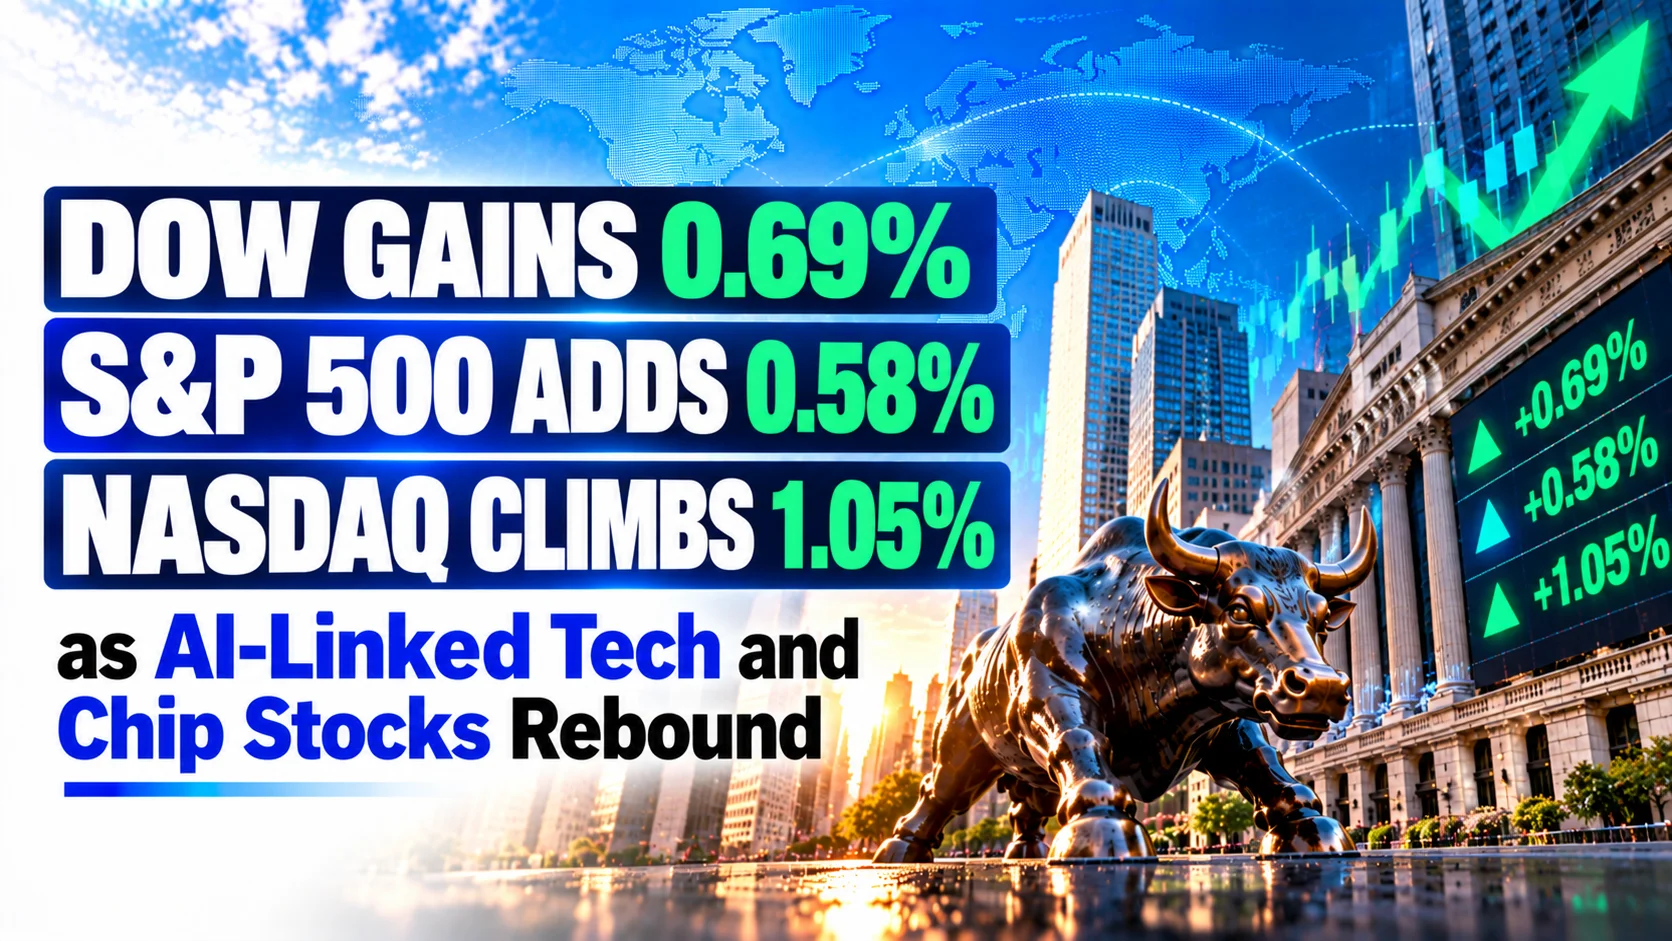
Dow Gains 0.69%, S&P 500 Adds 0.58%, Nasdaq Climbs 1.05% as AI-Linked Tech and Chip Stocks Rebound
Authored By HDFC SKY | Published at: Oct 22, 2026 09:42 AM IST
Open Free Demat Account
Open Free Demat Account
Mumbai, Oct 22: US equities closed higher on Wednesday, 21 October 2026, with the Dow Jones Industrial Average adding 360.21 points, or 0.69%, to close at 52,856.09, the S&P 500 gaining 44.60 points, or 0.58%, to 7,757.17, and the Nasdaq Composite rising 278.04 points, or 1.05%, to 26,702.86.
The technology-heavy Nasdaq led the advance as semiconductor and AI-linked technology shares rebounded, supported by easing Treasury yields and lower crude oil, while weakness in telecommunications and streaming stocks capped the broader upside. The session reflected a rotation back into chipmakers and growth names, with the Dow and S&P 500 also finishing higher as technology and industrial strength offset pressure in defensive sectors.
Dow Gains 360 Points as SpaceX Results Lift Technology Shares
The Dow Jones Industrial Average opened at 52,652.85 and closed at 52,856.09, gaining 360.21 points, or 0.69%. The blue-chip benchmark touched an intraday high of 52,860.11 and a low of 52,392.28 during the session. Gains were concentrated in technology and industrial constituents, with Nvidia rising 2.54%, IBM adding 3.77%, Goldman Sachs climbing 2.23%, Caterpillar advancing 2.03% and American Express adding 1.66%. Apple rose 1.32%, while Microsoft edged up 0.18%.
On the downside, Alphabet fell 1.62%, Procter & Gamble declined 1.53%, Nike slipped 0.91%, Coca-Cola lost 0.89% and Johnson & Johnson eased 0.66%, capping the index’s upside. The session followed SpaceX’s first quarterly profit as a public company, which revived demand for AI-linked constituents and supported the Dow’s technology weighting, even as several defensive names lagged. The index’s advance was broad enough to offset weakness in consumer staples and communication services, with the technology and industrial blocks providing the bulk of the point gain.
S&P 500 Gains 0.58% as AI Infrastructure Demand Drives Advance
The S&P 500 opened at 7,736.43 and ended at 7,757.17, gaining 44.60 points, or 0.58%. During the session, the index reached a high of 7,770.40 and a low of 7,709.34. The advance was led by the Information Technology sector, which rose 1.5%, with Super Micro Computer surging 9.55%, Charles River Laboratories jumping 9.33%, Datadog adding 6.50%, Dell Technologies gaining 5.26% and CrowdStrike rising 5.26%.
Coinbase added 4.60% and D.R. Horton advanced 4.36%. The benchmark’s gains were partially offset by a 6.45% slide in AT&T, a 5.29% decline in Netflix, a 3.56% drop in PDD Holdings, a 3.38% fall in Booking Holdings and a 1.84% decline in Abbott Laboratories, reflecting weakness across communication services and consumer discretionary names. The index’s closing performance came as SpaceX’s revenue jump and Super Micro’s raised outlook reinforced expectations that AI infrastructure spending remains intact. Breadth within the benchmark was positive but uneven, with technology and industrials doing the heavy lifting while defensive sectors and communication services lagged.
Nasdaq Gains 1.05% as Chip Stocks and SpaceX Surge Strongly
The Nasdaq Composite opened at 26,601.73 and closed at 26,702.86, marking a gain of 278.04 points, or 1.05%. Its intraday high stood at 26,778.90, while the low was 26,507.07. Technology and growth-oriented shares drove the advance, with Nvidia up 2.54%, Advanced Micro Devices adding 3.39%, Broadcom rising 1.00%, Micron Technology gaining 2.00% and ASML up 2.81%. Palantir Technologies rose 4.74%, CrowdStrike climbed 5.26% and Strategy added 7.54%.
The index’s gains were tempered by Netflix, which fell 5.29% to $65.04, PDD Holdings, which dropped 3.56%, Booking Holdings, which lost 3.38%, T-Mobile US, which declined 2.54%, and Intuitive Surgical, which fell 2.26%.
The technology-heavy benchmark responded to SpaceX’s 161% revenue growth and its AI segment’s expansion, which lifted semiconductor and cloud-related shares across the board. The Nasdaq’s gain was the strongest among the major averages, reflecting its heavier weighting toward chipmakers and AI-linked growth names.
Russell 2000 Gains 0.27% as Smaller Stocks Edge Higher Today
The Russell 2000 opened at 2,780.33 and closed at 2,781.03, gaining 7.61 points, or 0.27%. It recorded an intraday high of 2,791.72 and a low of 2,772.32. Movements among smaller-cap companies were mixed, with Applied Digital surging 8.54%, Bloom Energy jumping 7.31%, TTM Technologies adding 6.95%, Wulf gaining 6.29% and Credo Technology rising 6.19%.
Dycom Industries fell 5.91%, Kodiak Sciences dropped 5.65%, Xometry declined 5.02%, PCVX lost 4.50% and EAT slipped 3.77%. The benchmark’s modest gain reflected selective buying in AI-adjacent and energy-transition names, while broader small-cap participation remained restrained as large-cap technology exposure led the session. Small-cap breadth was positive but thin, with gains concentrated in a handful of technology and energy-linked names rather than across the broader universe.
S&P 100 Gains 0.58% as Large-Cap Technology Shares Lead
The S&P 100 opened at 3,843.24 and finished at 3,854.65, recording a gain of 22.25 points, or 0.58%. The index traded between 3,825.85 and 3,859.65 during the session. Movements in major large-cap constituents, including Nvidia at 2.54%, Apple at 1.32%, Microsoft at 0.18%, Amazon at -0.08% and Alphabet at -1.62%, contributed to the index’s daily performance as markets responded to SpaceX’s earnings beat and Super Micro’s preliminary results.
The S&P 100’s advance was narrower than the Nasdaq’s, reflecting the drag from communication services and consumer staples heavyweights. The index’s close near its intraday high indicated that buying interest persisted into the final hour, even as some mega-cap names remained under pressure.
Dow Composite Gains 0.53% as Transport and Utility Diverge Sharply
The Dow Jones Composite Average opened at 16,403.54 and closed at 16,448.47, gaining 86.08 points, or 0.53%, after moving between 16,357.34 and 16,470.53. The Dow Jones Transportation Average ended at 19,922.56, compared with an opening level of 19,906.07, representing a 0.19% gain, as United Airlines rose 3.79% and CSX added 0.01%.
The Dow Jones Utility Average closed at 1,081.39, changing 0.28% from its opening level of 1,081.43, with Constellation Energy gaining 4.60% and NextEra Energy slipping 0.77%. Movements in relevant constituents reflected the broader rotation into technology and industrial names, while utilities and transports lagged.
The transportation average’s gain was modest despite United Airlines’ advance, while the utility average’s move was largely flat as gains in Constellation Energy offset weakness in other components.
SOX Gains 1.97% as Chip Stocks Rebound Across Market Today
The Philadelphia Semiconductor Index (SOX) opened at 11,494.44 and closed at 11,505.56, gaining 221.74 points, or 1.97%. Its intraday high was 11,562.24, while the low was 11,355.29.
Semiconductor-related constituents such as Nvidia at 2.54%, Advanced Micro Devices at 3.39%, Micron Technology at 2.00%, Marvell Technology at 1.81% and ON Semiconductor at 2.24% contributed to the sector benchmark’s daily performance amid renewed demand optimism following SpaceX’s AI revenue disclosure and Super Micro’s raised revenue forecast.
The SOX’s advance marked a sharp reversal from its recent eight-session losing streak, the longest in 18 years. The index closed near its intraday high, signalling that chipmakers attracted buying throughout the session rather than only in early trade.
NYSE Composite Gains 0.27% as Broader Shares Track Technology Strength
The NYSE Composite opened at 24,251.37 and closed at 24,255.26, recording a gain of 64.64 points, or 0.27%. The index traded between 24,179.46 and 24,279.21 during the session. Movements across technology, financial and industrial segments contributed to its performance as SpaceX’s earnings and Super Micro’s guidance shaped broader US equity trading.
Among the broader gainers, Strive rose 13.64%, Alamar Biosciences added 11.68%, Skydance gained 10.85%, Netskope advanced 10.04% and Innodata climbed 10.02%. Arcus Biosciences fell 19.58%, Telix Pharmaceuticals dropped 10.13%, Lithia Motors declined 10.15% and TAL Education lost 8.89%.
Advancing issues outnumbered decliners by a 1.56-to-1 ratio on the NYSE, with 90 new highs and 161 new lows, reflecting a market that was positive at the surface but internally uneven.
S&P MidCap 400 Gains 0.40% as SmallCap 600 Adds 0.08%
The S&P MidCap 400 opened at 3,665.90 and closed at 3,665.94, moving 14.59 points, or 0.40%, with an intraday range of 3,651.11 to 3,678.69. The S&P SmallCap 600 opened at 1,679.04 and ended at 1,675.64, gaining 1.36 points, or 0.08%, after trading between 1,668.27 and 1,682.18.
The two benchmarks reflected movements among mid- and small-cap shares as AI-related demand and technology-sector strength affected the wider market, though gains were more muted than those seen in large-cap indices.
Within the small-cap space, Applied Digital and Bloom Energy led gains, while Dycom Industries and Kodiak Sciences were among the weakest names. Mid-cap participation was similarly selective, with technology and industrial names outperforming while consumer and healthcare constituents lagged.
SpaceX Revenue Jumps 161% as AI Demand Revives Technology Buying
The session’s principal trigger was SpaceX’s third-quarter report, which showed revenue rising 161% to $14.58 billion and the company swinging to a profit, with its AI business expanding sharply. Super Micro Computer also raised its quarterly revenue forecast to $18.5 billion–$19.5 billion from a prior range of $14.5 billion–$15.5 billion, citing increased demand for AI platforms. The two developments revived appetite for AI-linked shares after a recent selloff driven by concerns about the sustainability of AI spending. Tesla shares rose 3.37% after Elon Musk said SpaceX and Tesla had formed special committees to discuss a potential merger, though no terms were reached.
The technology sector led the advance, while communication services and consumer staples lagged. The session’s price action showed that investors were willing to re-engage with AI infrastructure names when presented with concrete revenue and guidance signals, even as several company-specific disappointments in streaming and telecommunications capped the broader index gains.
Treasury Yield Falls to 5.102% as Oil Retreats, Supporting Gains
The 10-year US Treasury yield fell to 5.102%, while the 30-year yield slipped to 5.413% and the 2-year yield declined to 4.778%. The move coincided with a retreat in crude oil from recent highs, with Brent crude settling at $108.71 and WTI crude at $97.14, easing immediate inflation concerns linked to energy costs.
Markets priced a 14.9% probability of a 25-basis-point rate hike at the upcoming Federal Reserve meeting, down from earlier expectations. The Treasury also prepared a $13 billion auction of 20-year bonds, with a $26 billion sale of 5-year Treasury Inflation-Protected Securities scheduled for Thursday.
The yield decline supported rate-sensitive technology and growth shares, contributing to the Nasdaq’s outperformance, while the oil retreat eased pressure on transport and consumer-facing names.
VIX Falls 3.52% as Market Volatility Indicator Eases During Session
The CBOE Volatility Index (VIX) changed -3.52% to 16.70, compared with its previous close of 17.31. The index measures expected volatility in the S&P 500 over the coming 30 days. Its movement during the session coincided with the equity market’s broad advance and the easing of safe-haven demand following SpaceX’s earnings and reports of diplomatic progress in the Middle East.
The VIX traded between 16.51 and 17.58 during the session, reflecting intraday fluctuations as the technology-led rally held through the close. The decline in the volatility gauge was consistent with the positive tone across major indices, though the intraday range indicated that uncertainty persisted beneath the surface.
S&P 500 Sectors Show Broad Gains Led by Technology and Industrials
Performance across the 11 S&P 500 sectors was broadly higher, with Information Technology recording the strongest move at 1.5%, followed by Industrials and Energy, each gaining more than 1%. Communication Services was the weakest sector, declining 1.2%, dragged down by AT&T’s 6.45% slide and Netflix’s 5.29% drop.
Consumer Discretionary rose about 0.6%, Financials added 0.3%, Utilities gained 0.28% and Materials edged up 0.1%, while Consumer Staples slipped 0.4%, Health Care eased 0.2% and Real Estate declined 0.1%.
The sector movements followed the rotation back into AI-linked technology names and away from defensives, with communication services pressured by company-specific outlook disappointments.
Magnificent Seven Show Mixed Performance as Nvidia and Tesla Advance
Among the Magnificent Seven, Nvidia moved 2.54%, Tesla changed 3.37%, Apple recorded 1.32%, Meta Platforms added 0.53%, Microsoft edged up 0.18%, Amazon slipped 0.08% and Alphabet fell 1.62%.
Their daily movements contributed to the performance of major US equity benchmarks, with Nvidia and Tesla providing the strongest support to the Nasdaq and S&P 500, while Alphabet’s decline weighed on communication services and the Dow. Meta and Microsoft posted only modest gains, reflecting a selective approach to mega-cap technology exposure rather than a uniform rally across the group.
Semiconductor, Financial and Energy Stocks Show Mixed Daily Moves
Semiconductor stocks were higher, with the Philadelphia Semiconductor Index moving 1.97%. Financial stocks recorded modest gains, with Goldman Sachs rising 2.23%, Morgan Stanley adding 3.72%, Citigroup gaining 1.08% and Bank of America up 0.35%, while JPMorgan Chase slipped 0.07%.
Energy stocks moved higher alongside stability in crude oil prices, with the Energy Select Sector SPDR gaining 0.29%. AI and growth stocks were higher, with movements among Palantir Technologies at 4.74%, CrowdStrike at 5.26% and Datadog at 6.50% contributing to the technology-heavy indices. The mixed performance within financials showed that gains were concentrated in capital-markets names rather than across the entire sector.
Economic Data Shows Mortgage Demand Falling 5.3% as Rates Remain Elevated
The latest economic data showed total mortgage application volume falling 5.3% in the week ended 16 October, compared with the previous week, according to the Mortgage Bankers Association’s seasonally adjusted index. Purchase applications declined 7% week-on-week and 18% year-on-year, while refinance applications fell 2% week-on-week and 59% year-on-year. The average contract interest rate for 30-year fixed-rate mortgages decreased to 7.41% from 7.50%, though the decline was insufficient to stimulate borrowing activity.
Pending home sales fell 7.3% in September from the previous month, according to the National Association of Realtors, reaching their lowest level since records began in 2001. Separate Energy Information Administration data showed US crude inventories fell by 3.06 million barrels, gasoline stocks dropped nearly 3 million barrels to 205.3 million, and distillate inventories rose 1.68 million barrels, with refinery utilisation steady at 93.4%.
Federal Reserve and Treasury Yields Set the Rate Backdrop for Markets
The Federal Reserve remained a key focus as markets assessed the likelihood of further policy tightening ahead of the central bank’s upcoming meeting. Markets priced a 14.9% probability of a 25-basis-point rate hike, down from earlier expectations. The 2-year US Treasury yield stood at 4.778%.
The 10-year Treasury yield stood at 5.102%, and the 30-year yield was 5.413%. The yield curve flattened as shorter-dated yields held relatively firm while longer-dated yields declined, reflecting a modest safe-haven bid and the absence of major economic releases during the session.
The Treasury’s financing schedule remained in focus, with the $13 billion 20-year auction and the upcoming $26 billion 5-year TIPS sale shaping expectations for duration supply.
Crude Oil, Gold And Metals Move With Middle East and Supply Signals
Brent crude traded at $108.71, changing -0.35%, while WTI crude stood at $97.14, moving -1.05%. Gold traded at $4,137.21, changing 0.30%, while silver moved -0.60% to $57.63. Copper changed -1.09% to $6.465, and natural gas moved -6.09% to $2.824.
The commodity moves followed a retreat in crude prices from recent five-month highs, alongside a stronger dollar and profit-taking in industrial metals, while natural gas fell on mild weather forecasts and ample inventories.
The oil pullback came even as reports of an attack on a Saudi Aramco oil field in the Eastern Region briefly lifted Brent futures, with prices later settling lower as the initial supply concerns eased.
Dollar and Major Currencies Move Against Fed Expectations During Session
The US Dollar Index (DXY) moved -0.27% to 101.70. EUR/USD stood at 1.1237, USD/JPY traded at 158.17, and GBP/USD was at 1.3380. Currency movements followed a decline in Treasury yields and reduced safe-haven demand as trading assessed the Fed’s rate trajectory and the implications of the AI-led equity rally for global capital flows. The dollar’s modest decline was consistent with the easing in yields, while the yen and euro posted limited moves against the greenback.
The closing session was shaped by SpaceX’s results and Super Micro’s raised guidance, alongside easing Treasury yields and lower crude oil. The Dow, S&P 500 and Nasdaq finished higher, while sector, bond, commodity and currency markets recorded the changes outlined above. These figures provide a factual summary of the session and its key market developments.
Source:
- https://www.nasdaq.com/
- spglobal.com/spdji/en/indices/equity/sp-500/
- https://www.dowjones.com/
- https://www.spglobal.com/spdji/en/indices/equity/dow-jones-industrial-average/
- https://www.spglobal.com/spdji/en/indices/equity/sp-500/
- https://www.nasdaq.com/market-activity/index/comp
- https://www.nasdaq.com/market-activity/quotes/nasdaq-ndx-index
- https://www.spglobal.com/spdji/en/indices/equity/sp-100/
- https://www.lseg.com/en/ftse-russell/indices/russell-us
- https://www.nyse.com/index
- https://www.nyse.com/index
- https://www.spglobal.com/spdji/en/indices/equity/dow-jones-transportation-average/
- https://www.spglobal.com/spdji/en/indices/equity/dow-jones-utility-average/
- https://www.spglobal.com/spdji/en/indices/equity/dow-jones-composite-average/
- https://www.nasdaq.com/market-activity/index/sox
- https://www.cboe.com/tradable_products/vix/
Disclaimer
The information shared here is intended solely for informational and educational purposes and does not constitute investment recommendations. While we practice strict due diligence in curating daily market data, readers must perform independent research before trading. To flag any real-time data discrepancies or content concerns, please write to us at content@hdfcsec.com.
 Join Us
 Add as preferred source on Google


More Markets News


Open Free Demat Account
Open Free Demat Account




Invest Anytime, Anywhere


By signing up I certify terms, conditions & privacy policy