Nifty 50
- Infosys₹1,16837.30 (3.30%)
- Bajaj Finance₹926-31.35 (-3.27%)
- HCL Technologies₹1,424.2044.30 (3.21%)
- BSE₹3,248.30-87.70 (-2.63%)
- Tech Mahindra₹1,834.7055.60 (3.13%)
- Eternal₹312.35-7.85 (-2.45%)
- TCS₹2,52968.10 (2.77%)
- Eicher Motors₹7,170.50-178.50 (-2.43%)
- UltraTech Cement₹10,849199.00 (1.87%)
- Trent₹2,822-69.60 (-2.41%)
- Bharti Airtel₹1,891.7016.50 (0.88%)
- Maruti Suzuki₹11,200-275.00 (-2.40%)
- SBI Life Insurance ₹1,66113.20 (0.80%)
- Adani Enterprises₹2,594.50-63.00 (-2.37%)
- Power Grid Corp₹252.151.80 (0.72%)
- Shriram Finance₹904.95-21.55 (-2.33%)
- Reliance Industries₹1,2097.00 (0.58%)
- Axis Bank₹1,210-26.00 (-2.10%)
- ITC₹2621.20 (0.46%)
- Bajaj Auto₹10,072-215.00 (-2.09%)

- Offerings
- Tools & Platforms
Tools & Calculators
- Open API
- Calculators
- SIP Calculator
- CAGR Calculator
- Compound Interest Calculator
- FD Calculator
- RD Calculator
- EPF Calculator
- Retirement Calculator
- HDFC SIP Calculator
- Mutual Fund Return Calculator
- Lumpsum Calculator
- Step Up SIP Calculator
- ETF SIP Calculator
- Brokerage Calculator
- Equity Margin Calculator
- SWP Calculator
- EMI Calculator
- MTF Calculator
- Margin Pledge Calculator
- Algo Strategy
- Markets
Stocks
F&O
Mutual Funds
- More
Siemens: Revenue and EBITDA Impacted by Slowdown in Private Sector Capital Expenditure
Authored By HDFC SKY | Last Modified: Aug 11, 2025 07:32 PM IST
Open Free Demat Account
Open Free Demat Account
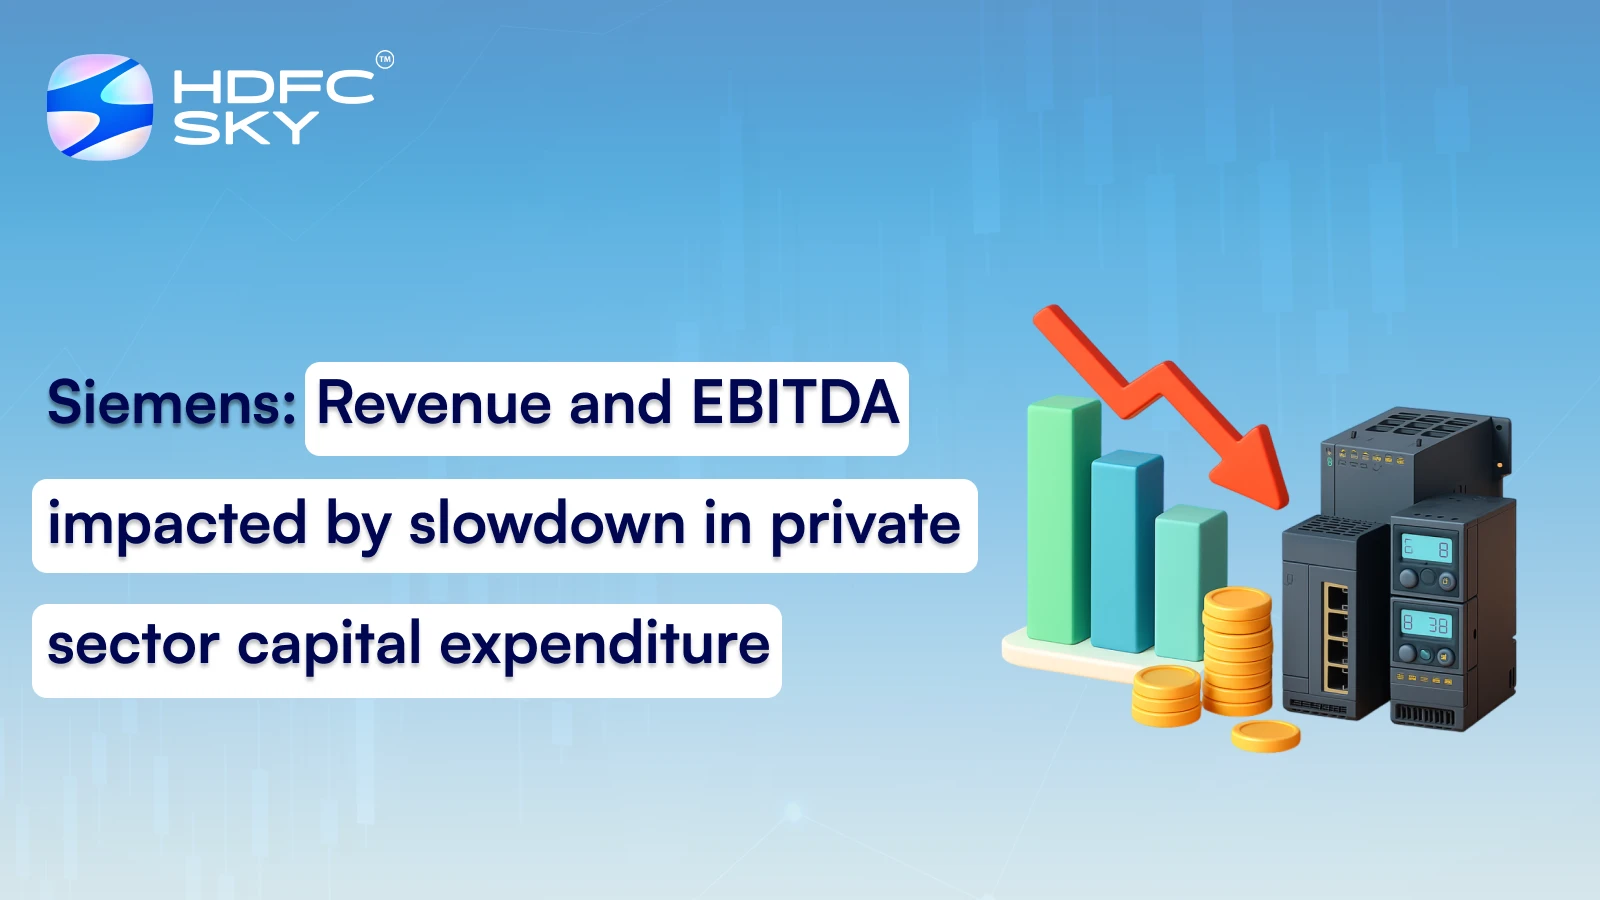
Siemens India’s (SIL) revenue/EBITDA/APAT of INR 33.3/4/3.9bn fell shortly by 1.4/7.9/13.6% respectively, from our estimates. Revenue and EBITDA were impacted by slowdown in the short cycle private sector capex spending. Smart infrastructure delivered strong execution and mobility segment witnessed two significant order wins.
For some time now, the Digital Industries segment has been a laggard. In this quarter, the worst seems to be behind for the segment, with business now showing signs of recovery indicating that de-stocking phase is now largely over.
SIL’s order inflow (OI) stood at INR 56.8bn (+13% YoY) as of Jun’25, with order book (OB) standing at INR 428.5bn. It is supported by two significant order wins in the Mobility business. SIL has executed the demerger of its energy segment into a separate entity, which was listed in Jun’25. Its segments are exposed to government capital expenditure, which is expected to grow 10% YoY, while the private capital expenditure recovery is contingent on pick-up in consumption.
We have marginally recalibrated our estimates higher. Given the robust order backlog and stable order inflows, we maintain a BUY rating, with increased TP of INR 3,862 (rolled over to 55x Jun-27 EPS).
Disclaimer : This content is only for informational purpose. It does not make any recommendation to act or invest. To get any error corrected, please write to content@hdfcsec.com. The target price recommendation given are not specifically for you as they do not factor your unique risk tolerance and investment objectives.
Source: HDFC Securities Institutional Equities
To see full report, click on : https://www.hdfcsec.com/hsl.docs/HSIE%20Results%20Daily%20-%2011%20Aug%2025%20-%20HSIE-202508110703171287901.pdf?t=11820257719457
 Join Us
 Add as preferred source on Google


More Markets News


Open Free Demat Account
Open Free Demat Account




Invest Anytime, Anywhere


By signing up I certify terms, conditions & privacy policy