Nifty 50
- Infosys₹1,086.8524.75 (2.33%)
- Shriram Finance₹953.05-34.95 (-3.54%)
- Coal India₹417.709.20 (2.25%)
- HDFC Life Insurance ₹547.85-12.15 (-2.17%)
- Nestle₹1,362.5028.50 (2.14%)
- Bajaj Finserv₹1,722.30-33.40 (-1.90%)
- Tata Consumer ₹97818.00 (1.88%)
- SBI Life Insurance ₹1,657.50-29.70 (-1.76%)
- TCS₹2,307.6038.30 (1.69%)
- Dr. Reddy's Labs₹1,219.70-20.30 (-1.64%)
- NTPC₹315.604.60 (1.48%)
- Bajaj Finance₹966.95-15.80 (-1.61%)
- Hindustan Unilever₹1,894.8019.30 (1.03%)
- Sun Pharmaceutical₹1,750-20.70 (-1.17%)
- ONGC₹224.922.27 (1.02%)
- Cipla₹1,315.30-14.30 (-1.08%)
- Reliance Industries₹1,178.3011.60 (0.99%)
- SBI₹947.45-9.55 (-1.00%)
- Kotak Mahindra Bank₹443.304.30 (0.98%)
- Adani Ports₹1,746-17.00 (-0.96%)
- Offerings
- Tools & Platforms
Tools & Calculators
- Open API
- Calculators
- SIP Calculator
- CAGR Calculator
- Compound Interest Calculator
- FD Calculator
- RD Calculator
- EPF Calculator
- Retirement Calculator
- HDFC SIP Calculator
- Mutual Fund Return Calculator
- Lumpsum Calculator
- Step Up SIP Calculator
- ETF SIP Calculator
- Brokerage Calculator
- Equity Margin Calculator
- SWP Calculator
- EMI Calculator
- MTF Calculator
- Margin Pledge Calculator
- Algo Strategy
- Markets
Stocks
F&O
Mutual Funds
- More
Tata Elxsi Shares Jump 8% After Results But Brokers Remain Cautious
Authored By HDFC SKY | Last Modified: Oct 14, 2026 11:12 AM IST
Open Free Demat Account
Open Free Demat Account
Mumbai, October 14: Tata Elxsi shares rallied as much as 8% on Wednesday after the engineering research and development company reported a year-on-year increase in September-quarter profit and revenue. However, brokerages retained their bearish ratings, citing expensive valuations, subdued demand in the European automotive market and uncertainty over the pace at which new deals will translate into revenue growth.
Tata Elxsi Q2 Results
Tata Elxsi reported a consolidated net profit of Rs 170 crore for the September quarter, up from Rs 155 crore in the year-ago period. Revenue from operations increased 15% year-on-year to Rs 1,056 crore from Rs 918 crore.
The transportation business recorded growth supported by new deal wins and traction in adjacent markets, including aerospace. The media and communications business also benefited from project ramp-ups and fresh engagements.
Despite the improvement in revenue and profitability, analysts remain cautious about the sustainability of growth, given the time required for new projects to scale up and ongoing weakness in parts of the global automotive industry.
Global Broker Maintains Underweight Rating
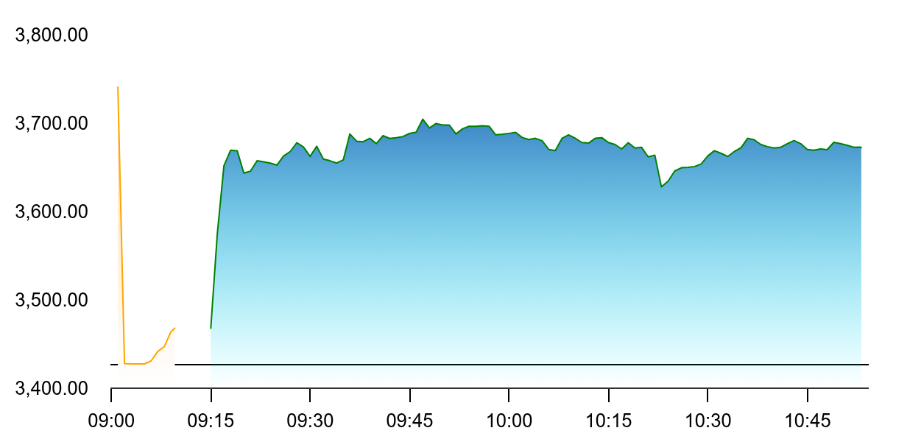
The stock jumped for joy after results. Source: NSE
A global broker retained its Underweight rating on Tata Elxsi, with a target price of Rs 3,400. The brokerage acknowledged that revenue growth and margins exceeded expectations, with constant-currency revenue rising 2.3% sequentially against its estimate of 1.6%.
However, net profit missed consensus expectations, partly due to a higher tax rate. The broker expects margin improvement to remain gradual. Although the brokerage raised its earnings estimates for FY28 and FY29, it remained cautious about the stock’s valuation.
Local Broker Reiterates Sell Call
A local broker maintained its Sell rating on Tata Elxsi, with a target price of Rs 2,970. The brokerage expects growth to improve in the second half of FY27, but said a sustained acceleration will depend on converting recent deal wins into recognised revenue.
New engagements typically take two to three quarters to ramp up, delaying their contribution to financial performance. The broker expects recently secured deals to contribute more meaningfully in FY28 and projects constant-currency revenue growth of 8.2% for that year.
The brokerage also flagged subdued European automotive demand, cautious client spending and delayed decisions by original equipment manufacturers as risks. While demand in the US and India remains relatively supportive, weakness in Europe could continue to weigh on engineering expenditure.
What Lies Ahead For Tata Elxsi Shares?
Tata Elxsi’s quarterly performance points to improving revenue momentum, but analysts remain concerned about valuations. Investors will track new-deal conversion, operating margins and a potential improvement in European automotive demand to assess whether the stock’s rally can be sustained.
Source
- NSE
Disclaimer
The information shared here is intended solely for informational and educational purposes and does not constitute investment recommendations. While we practice strict due diligence in curating daily market data, readers must perform independent research before trading. To flag any real-time data discrepancies or content concerns, please write to us at content@hdfcsec.com.
 Join Us
 Add as preferred source on Google


More TATAELXSI News



Open Free Demat Account
Open Free Demat Account
₹3,654.80
Invest Anytime, Anywhere
By signing up I certify terms, conditions & privacy policy