Nifty 50
- Tata Consumer ₹1,00063.50 (6.78%)
- Asian Paints₹2,277-45.00 (-1.94%)
- Bharti Airtel₹1,978.8061.30 (3.20%)
- Coal India₹398-7.00 (-1.73%)
- Bajaj Auto₹10,390319.00 (3.17%)
- Grasim Industries₹2,900.80-49.20 (-1.67%)
- BSE₹3,441.1082.10 (2.44%)
- SBI₹945.10-15.70 (-1.63%)
- Trent₹2,820.6066.60 (2.42%)
- TCS₹2,496.90-38.10 (-1.50%)
- Maruti Suzuki₹11,450230.00 (2.05%)
- Adani Enterprises₹2,474.10-33.90 (-1.35%)
- Power Grid Corp₹251.754.75 (1.92%)
- Axis Bank₹1,205.70-14.30 (-1.17%)
- Eternal₹3315.45 (1.67%)
- ICICI Bank₹1,386.90-16.10 (-1.15%)
- Max Healthcare₹847.9012.90 (1.54%)
- HDFC Bank₹680.20-7.85 (-1.14%)
- Bharat Electronics₹368.155.15 (1.42%)
- HDFC Life Insurance ₹513.60-5.40 (-1.04%)

- Offerings
- Tools & Platforms
Tools & Calculators
- Open API
- Calculators
- SIP Calculator
- CAGR Calculator
- Compound Interest Calculator
- FD Calculator
- RD Calculator
- EPF Calculator
- Retirement Calculator
- HDFC SIP Calculator
- Mutual Fund Return Calculator
- Lumpsum Calculator
- Step Up SIP Calculator
- ETF SIP Calculator
- Brokerage Calculator
- Equity Margin Calculator
- SWP Calculator
- EMI Calculator
- MTF Calculator
- Margin Pledge Calculator
- Algo Strategy
- Markets
Stocks
F&O
Mutual Funds
- More
HSIE Institutional Report: Century Plyboards India Feb, 06 2026
Authored By Prime Research | Last Modified: Feb 6, 2026 04:08 PM IST
Open Free Demat Account
Open Free Demat Account
Strong all Round Performance
Century’s revenue grew 18% YoY to INR 13.5bn, led by healthy growth in MDF segment (up 19% YoY), ply segment (up 15% YoY), laminates segment (up 10% YoY) and particle board (up 84% YoY). MDF/ ply/ laminates/ particle board volume grew 13/14/115% YoY, while laminates declined 8% YoY. Healthy revenue traction and improved margins drove a 32/22% YoY rise in EBITDA/APAT. The company has broadly maintained its guidance for FY26. It also plans major plywood expansion of more than 50% by FY29 to cut outsourcing. MDF capacity is likewise set to expand more than 50% by FY29. Factoring in Q3 performance, we broadly maintain our revenue and EBITDA estimates. However, we trim our APAT estimates by 4/8% for FY27/28E, respectively, to account for the new announced ply and MDF expansions, leading to increase in our depreciation and interest cost projection. We value Century Ply using SOTP—ex-particle board business at 40x Mar-28E EPS and the upcoming particle board business at 2x capital employed in Mar-28E—to arrive at a TP of INR 935/sh.
Century Plyboards India Q3FY26 Highlights
Revenue grew 18% YoY (+19% QoQ) to INR 13.5bn, led by healthy growth in MDF segment (up 19% YoY), ply segment (up 15% YoY), laminates segment (up 10% YoY), and particle board (up 84% YoY). MDF/ply/laminates/particle board volume grew 13/14/115% YoY, while laminates declined 8% YoY. MDF/ ply/ laminates operating margin expanded by 130/350/330 bps YoY to 12.1/15.1/ 7.7%, while particle board margin declined 450bps YoY to 0.4%. Healthy revenue traction and improved margins drove a 32/22% YoY rise in EBITDA/APAT.
Con Call KTAs and Outlook
The company has reaffirmed its FY26 guidance, projecting 13% revenue growth with 12-14% EBITDAM in ply; 25% revenue growth with 14-15% EBITDAM in MDF; 15-17% revenue growth with high single-digit EBITDAM by Q4-end in laminates; and 40% revenue growth with low single-digit EBITDAM in particleboard. For FY27, laminate revenues are expected to grow by 20% with double-digit EBITDA margins, while particleboard margins are projected to reach ~15% by Q4FY27. It also plans major plywood expansion by more than 50% by FY29 to cut outsourcing— particularly in Sanik MR (water-resistant) ply. MDF capacity is likewise set to expand more than 50% by FY29. Factoring in Q3 performance, we broadly maintain our revenue and EBITDA estimates. However, we trim our APAT estimates by 4/8% for FY27/28E, respectively, to account for the newly announced ply and MDF expansions, leading to an increase in our depreciation and interest cost projection. We value Century Ply using SOTP— ex-particle board business at 40x Mar-28E EPS and the upcoming particle board business at 2x capital employed in Mar-28E—to arrive at TP of INR 935/sh.
Quarterly/Annual Financial Summary (Consolidated)
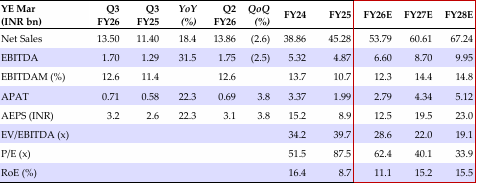
Source: HSIE Research (HSIE Results Daily Report – 06 Feb 26 )
Disclaimer
If you have any concerns, questions, or wish to point out any discrepancies in our content, please feel free to write to us at content@hdfcsec.com.
Disclaimer
The information shared here is intended solely for informational and educational purposes and does not constitute investment recommendations. While we practice strict due diligence in curating daily market data, readers must perform independent research before trading. To flag any real-time data discrepancies or content concerns, please write to us at content@hdfcsec.com.
 Join Us
 Add as preferred source on Google


More Markets News


Open Free Demat Account
Open Free Demat Account




Invest Anytime, Anywhere


By signing up I certify terms, conditions & privacy policy