Nifty 50
- Tata Consumer ₹1,00063.50 (6.78%)
- Asian Paints₹2,277-45.00 (-1.94%)
- Bharti Airtel₹1,978.8061.30 (3.20%)
- Coal India₹398-7.00 (-1.73%)
- Bajaj Auto₹10,390319.00 (3.17%)
- Grasim Industries₹2,900.80-49.20 (-1.67%)
- BSE₹3,441.1082.10 (2.44%)
- SBI₹945.10-15.70 (-1.63%)
- Trent₹2,820.6066.60 (2.42%)
- TCS₹2,496.90-38.10 (-1.50%)
- Maruti Suzuki₹11,450230.00 (2.05%)
- Adani Enterprises₹2,474.10-33.90 (-1.35%)
- Power Grid Corp₹251.754.75 (1.92%)
- Axis Bank₹1,205.70-14.30 (-1.17%)
- Eternal₹3315.45 (1.67%)
- ICICI Bank₹1,386.90-16.10 (-1.15%)
- Max Healthcare₹847.9012.90 (1.54%)
- HDFC Bank₹680.20-7.85 (-1.14%)
- Bharat Electronics₹368.155.15 (1.42%)
- HDFC Life Insurance ₹513.60-5.40 (-1.04%)

- Offerings
- Tools & Platforms
Tools & Calculators
- Open API
- Calculators
- SIP Calculator
- CAGR Calculator
- Compound Interest Calculator
- FD Calculator
- RD Calculator
- EPF Calculator
- Retirement Calculator
- HDFC SIP Calculator
- Mutual Fund Return Calculator
- Lumpsum Calculator
- Step Up SIP Calculator
- ETF SIP Calculator
- Brokerage Calculator
- Equity Margin Calculator
- SWP Calculator
- EMI Calculator
- MTF Calculator
- Margin Pledge Calculator
- Algo Strategy
- Markets
Stocks
F&O
Mutual Funds
- More
HSIE Institutional Report: Eureka Forbes Feb, 06 2026
Authored By Prime Research | Last Modified: Feb 6, 2026 05:52 PM IST
Open Free Demat Account
Open Free Demat Account
A One Off Slow Quarter; Growth to Pick Up
Eureka’s revenue growth slowed down to 8% YoY in Q3, owing to slowdown in water purifier sales post festive and high channel inventory impact. However, management highlighted it has gained market share in water purifier category. Robotic, water softeners and air purifiers (grew 3x YoY) delivered healthy growth. Service business momentum builds up with third successive quarter of double-digit AMC bookings growth. EBITDA margin expanded by 70bps YoY owing to improved gross margin to 10.6%, leading to 16/15% growth in EBITDA/APAT. The management highlighted channel inventory pressures have eased across channels, except e-com, which will be normalize by Q4FY26 end. Management guided Q4 revenue growth will be higher than 11% delivered in 9MFY26. Considering a muted Q3 performance and continued elevated inventory in e-com channel, we have trimmed our revenue estimates by 2% each for FY26-28E and APAT estimates by 3/2% for FY27/27E, respectively, while broadly maintaining for FY28E. We maintain BUY with an unchanged TP of INR 830/sh, valued at 45x Mar-28E AEPS (excluding non-cash intangible amortization and 50% of performance-based ESOP expenses).
Eureka Forbes Q3FY26 Highlights
Revenue growth slowed down to 8% YoY in Q3, owing to a slowdown in water purifier sales post festive and high channel inventory impact. However, management highlighted they have gained market share in the water purifier category. Smaller categories: robotic, water softeners and air purifiers (grew 3x YoY) delivered healthy growth. Service business momentum builds up with third successive quarter of double-digit AMC bookings growth. Gross margin grew 340/410bps YoY/QoQ to 61.2%, driven by COGS reduction program, lower discounting and change in channel mix (lower e-com sales). Employee expenses grew 7% YoY, while other expenses grew 21% YoY led by 23% growth in A&SP spends. So, EBITDA margin expanded by 70bps YoY (-200bps QoQ) to 10.6%, leading to 16/15% growth in EBITDA/APAT.
Earnings Call Takeaways and Valuation
The management highlighted channel inventory pressures have eased across channels, except e-com, which will normalize by Q4FY26-end. It guided Q4 revenue growth will be higher than 11% delivered in 9MFY26. Service bookings grew at mid to high teens YoY in 9MFY26. The robotics business maintained strong traction, representing about two-thirds of vacuum cleaner revenues. Considering muted Q3 performance and elevated inventory in e-com channel, we have trimmed our revenue estimates by 2% each for FY26-28E and APAT estimates by 3/2% for FY26/27E, respectively, while broadly maintaining for FY28E. We maintain BUY with an unchanged TP of INR 830/sh, valued at 45x Mar-28E AEPS (excluding non-cash intangible amortization and 50% of performance-based ESOP expenses).
Financial Summary
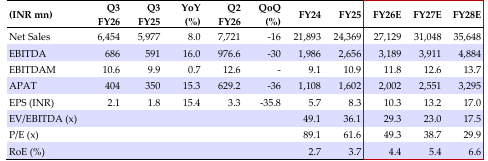
Source: HSIE Research (HSIE Results Daily Report – 06 Feb 26 )
Disclaimer
If you have any concerns, questions, or wish to point out any discrepancies in our content, please feel free to write to us at content@hdfcsec.com.
Disclaimer
The information shared here is intended solely for informational and educational purposes and does not constitute investment recommendations. While we practice strict due diligence in curating daily market data, readers must perform independent research before trading. To flag any real-time data discrepancies or content concerns, please write to us at content@hdfcsec.com.
 Join Us
 Add as preferred source on Google


More Markets News


Open Free Demat Account
Open Free Demat Account




Invest Anytime, Anywhere


By signing up I certify terms, conditions & privacy policy