Nifty 50
- Tata Consumer ₹1,00063.50 (6.78%)
- Asian Paints₹2,277-45.00 (-1.94%)
- Bharti Airtel₹1,978.8061.30 (3.20%)
- Coal India₹398-7.00 (-1.73%)
- Bajaj Auto₹10,390319.00 (3.17%)
- Grasim Industries₹2,900.80-49.20 (-1.67%)
- BSE₹3,441.1082.10 (2.44%)
- SBI₹945.10-15.70 (-1.63%)
- Trent₹2,820.6066.60 (2.42%)
- TCS₹2,496.90-38.10 (-1.50%)
- Maruti Suzuki₹11,450230.00 (2.05%)
- Adani Enterprises₹2,474.10-33.90 (-1.35%)
- Power Grid Corp₹251.754.75 (1.92%)
- Axis Bank₹1,205.70-14.30 (-1.17%)
- Eternal₹3315.45 (1.67%)
- ICICI Bank₹1,386.90-16.10 (-1.15%)
- Max Healthcare₹847.9012.90 (1.54%)
- HDFC Bank₹680.20-7.85 (-1.14%)
- Bharat Electronics₹368.155.15 (1.42%)
- HDFC Life Insurance ₹513.60-5.40 (-1.04%)

- Offerings
- Tools & Platforms
Tools & Calculators
- Open API
- Calculators
- SIP Calculator
- CAGR Calculator
- Compound Interest Calculator
- FD Calculator
- RD Calculator
- EPF Calculator
- Retirement Calculator
- HDFC SIP Calculator
- Mutual Fund Return Calculator
- Lumpsum Calculator
- Step Up SIP Calculator
- ETF SIP Calculator
- Brokerage Calculator
- Equity Margin Calculator
- SWP Calculator
- EMI Calculator
- MTF Calculator
- Margin Pledge Calculator
- Algo Strategy
- Markets
Stocks
F&O
Mutual Funds
- More
HSIE Institutional Report: IPCA Laboratories Feb, 17 2026
Authored By Prime Research | Last Modified: Feb 17, 2026 12:07 PM IST
Open Free Demat Account
Open Free Demat Account
Base Business Remains Strong; Unichem Ramp Up Key
EBITDA growth of 22% YoY was driven by 7% YoY sales growth (India grew 12% YoY), higher GM (+226 bps YoY at 72.5%), and cost controls (staff/SG&A +10%/+4% YoY), causing the margin to expand to 22.7% (+284 bps YoY). IPCA expects (1) overall business to see 10-11% growth in the near term (IPCA standalone growth at 10-12% and Unichem business at 8-9%); (2) India business to outperform IPM growth in the next few years, led by sustained momentum in key therapies (pain, CVS, anti-diabetics, CNS, and derma); looking to in licensing Semaglutide to participate in India GLP-1 market; (3) export formulation to see gradual improvement, led by traction in the EU and UK businesses, scale-up in the US business, and steady growth in branded generics; to sustain 10-12% YoY in near term; (4) API business to see slightly slower growth; (5) Unichem to see gradual pick-up in growth momentum from FY27/28E, led by product commercialization across EU and RoW markets (registration process started and approval may take 10-12 months) as well as new launches in the US; and (6) consolidated margin to improve by ~150 bps p.a. for the next couple of years; aims to achieve Unichem margin of 15% in the next 2-3 years and it hopes to reach 18-20% sustainable margin in the long term. We believe IPCA is well-positioned for growth (~10% CAGR over FY25-28E), given steady India growth (new launches, steady growth in focused therapies, and scale-up in chronic categories) and export formulation ramp-up (through Unichem integration and new launches in the EU/RoW), with improving margins (~16%/23% EBITDA/PAT CAGR over FY25-28E). Considering Q3 results, we have reduced the EPS by 5/2% for FY26/27E, while maintaining for FY28E and revised the TP to INR 1,750 (28x Q3FY28E EPS). Maintain BUY.
IPCA Laboratories Q3 Highlights
Sales grew 7% YoY to INR 23.92bn. India (41% of sales) grew 12% YoY, branded generics grew 28%, generics exports grew 21%, and institutional declined 21%, and API was flat (India/export -14%/+6%) and Unichem (22%) declined 2% YoY. Higher GM at 72.5% (+226 bps YoY) and moderate costs (staff/SG&A +10%/+4% YoY) led to EBITDA^ of INR 5.43bn (+22% YoY) with a margin of 22.7% (+284 bps). Muted other income and moderate interest/depreciation (+5%/9%) led to reported PAT of INR 3.26bn (+31% YoY). Adjusted for one-offs^, PAT stood at INR 3.18bn (+38% YoY).
Key Takeaways From Con Call
Overall, US sales (IPCA + Unichem) grew 17% YoY to INR 3.95bn (for 9M it grew 15% to INR 11.4 bn). It expects Unichem to gradually improve through cost optimization, shifting API sourcing to IPCA’s in-house facilities, ramping up operations in EU and RoW markets with new product registrations, and improving capacity utilization. The company expects to start tech-transfer and manufacturing for two biosimilars soon (five candidates under development) and is targeting global markets.
Quarterly Financial Summary
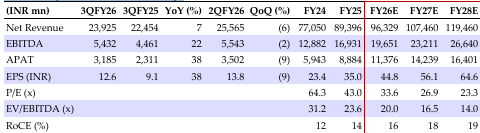
Source: HSIE Research (HSIE Results Daily Report – 17 Feb 26 )
Disclaimer
If you have any concerns, questions, or wish to point out any discrepancies in our content, please feel free to write to us at content@hdfcsec.com.
Disclaimer
The information shared here is intended solely for informational and educational purposes and does not constitute investment recommendations. While we practice strict due diligence in curating daily market data, readers must perform independent research before trading. To flag any real-time data discrepancies or content concerns, please write to us at content@hdfcsec.com.
 Join Us
 Add as preferred source on Google


More Markets News


Open Free Demat Account
Open Free Demat Account




Invest Anytime, Anywhere


By signing up I certify terms, conditions & privacy policy