Nifty 50
- Tata Consumer ₹1,00063.50 (6.78%)
- Asian Paints₹2,277-45.00 (-1.94%)
- Bharti Airtel₹1,978.8061.30 (3.20%)
- Coal India₹398-7.00 (-1.73%)
- Bajaj Auto₹10,390319.00 (3.17%)
- Grasim Industries₹2,900.80-49.20 (-1.67%)
- BSE₹3,441.1082.10 (2.44%)
- SBI₹945.10-15.70 (-1.63%)
- Trent₹2,820.6066.60 (2.42%)
- TCS₹2,496.90-38.10 (-1.50%)
- Maruti Suzuki₹11,450230.00 (2.05%)
- Adani Enterprises₹2,474.10-33.90 (-1.35%)
- Power Grid Corp₹251.754.75 (1.92%)
- Axis Bank₹1,205.70-14.30 (-1.17%)
- Eternal₹3315.45 (1.67%)
- ICICI Bank₹1,386.90-16.10 (-1.15%)
- Max Healthcare₹847.9012.90 (1.54%)
- HDFC Bank₹680.20-7.85 (-1.14%)
- Bharat Electronics₹368.155.15 (1.42%)
- HDFC Life Insurance ₹513.60-5.40 (-1.04%)

- Offerings
- Tools & Platforms
Tools & Calculators
- Open API
- Calculators
- SIP Calculator
- CAGR Calculator
- Compound Interest Calculator
- FD Calculator
- RD Calculator
- EPF Calculator
- Retirement Calculator
- HDFC SIP Calculator
- Mutual Fund Return Calculator
- Lumpsum Calculator
- Step Up SIP Calculator
- ETF SIP Calculator
- Brokerage Calculator
- Equity Margin Calculator
- SWP Calculator
- EMI Calculator
- MTF Calculator
- Margin Pledge Calculator
- Algo Strategy
- Markets
Stocks
F&O
Mutual Funds
- More
HSIE Institutional Report: NOCIL Feb, 13 2026
Authored By Prime Research | Published at: Feb 13, 2026 05:19 PM IST
Open Free Demat Account
Open Free Demat Account
Realization Offsets Volume Driven Growth
Our ADD recommendation on NOCIL with a TP of INR 217 is premised on (1) a shift in product mix toward better-margin specialized rubber chemicals; (2) expected antidumping duty in key products; and (3) capacity addition in coming quarters. Q3 EBITDA/APAT were 14/18% below our estimates, owing to lower-than-expected revenue and higher-than-expected other expenses.
Financial Performance
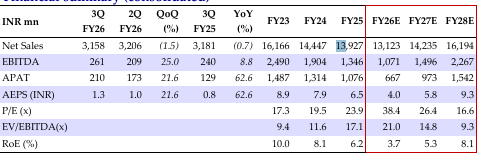
Revenue was in line with Q2 at INR 3.16bn. Realization remains impacted by pricing pressure due to aggressive dumping by Chinese players while it was partially offset by decrease in raw material prices. EBITDA/KG increased by 23% QoQ to INR 19/KG. EBITDA changed by +8.8/+25 % YoY/QoQ to INR 261mn. EBITDA margin changed by +70/+161bps to 8.3% due to decrease in other expense and raw material cost.
Key Con Call Takeaways
(1) The upcoming revision in US tariff structures is likely to drive volume recovery in the next 2-3 months, while the India‑EU FTA is expected to offer long‑term strategic and raw‑material cost benefits. (2) The company has filed anti‑dumping petitions against China, the EU, the US, Korea, and Thailand, with investigation outcomes are expected in the next 1.5-2 months. (3) The Dahej expansion project is ahead of schedule, with production trials planned for the first half of the year, adding 20% to overall capacity. (4) The company holds a 40% share of the Indian rubber chemical market, estimated at around 85,000 tons.
Change in Estimates
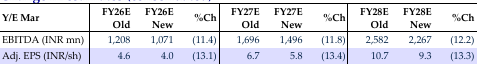
We change our FY26/27/28E EPS estimates by -13.1/ 13.4/-13.3% to INR 4.0/5.8/9.3x to factor in the Q3FY26 performance and growth outlook.
DCF Based Valuation
Our price target is INR 217. The stock is trading at 38.4/26.4/16.6x FY26/27/28E EPS.
Financial Summary (Consolidated)
Change in Estimates (Consolidated)
Source: HSIE Research (HSIE Results Daily Report – 13 Feb 26 )
Disclaimer
If you have any concerns, questions, or wish to point out any discrepancies in our content, please feel free to write to us at content@hdfcsec.com.
Disclaimer
The information shared here is intended solely for informational and educational purposes and does not constitute investment recommendations. While we practice strict due diligence in curating daily market data, readers must perform independent research before trading. To flag any real-time data discrepancies or content concerns, please write to us at content@hdfcsec.com.
 Join Us
 Add as preferred source on Google


More Markets News


Open Free Demat Account
Open Free Demat Account




Invest Anytime, Anywhere


By signing up I certify terms, conditions & privacy policy